SpaceX (SPCX) reported Q3 2026 on Tuesday 20 October US time, which was Wednesday morning here in Sydney. They streamed the call from the Starlink factory in Bastrop, Texas, with Elon, Gwynne Shotwell and CFO Bret Johnsen. I've listened to a lot of these calls with Elon at Tesla, and this one was the most excited and organised I've seen. I'm super bullish, and I reckon the upside here is bigger than Tesla's.
The numbers
| Q3 2026 | vs a year ago | |
|---|---|---|
| Revenue | US$14.6B (consensus ~US$12.7B) | up 161% from US$5.6B |
| Net income | US$4.4B | from a US$1.1B loss |
| Adjusted EBITDA | US$8.8B | up 306% |
| Adjusted EPS | US$0.45 (consensus US$0.13) | |
| Super Intelligence (AI) revenue | US$7.56B | roughly 9x |
| Connectivity (Starlink) revenue | US$5.25B | up 69% |
| Space (launch) revenue | US$1.77B | up about 6% |
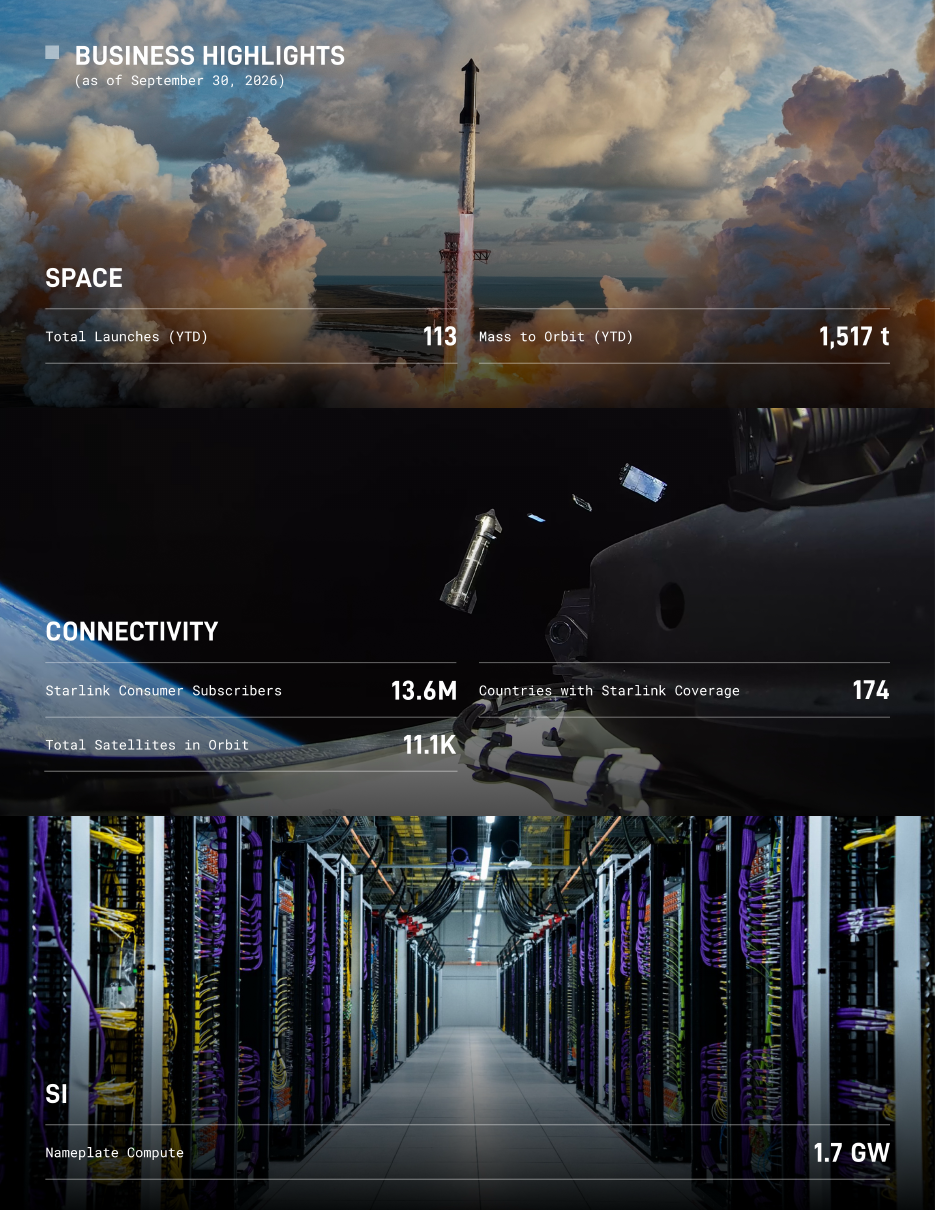
- Starlink. 13.6M consumer subscribers, with 1.6M added in the quarter. Coverage in 174 countries. Average revenue per user is US$69 a month.
- Compute. 1.7 GW of nameplate compute at 30 September.
- Backlog. US$63B.
- Q1 2027 guidance: revenue of US$33–37B. The street had about US$22B.
- The stock closed up 7.8% to US$159.31 on Wednesday.
What got me
- Starship is orbital and earning. Flight 14 delivered 26 Starlink V3 satellites, which is about 10 Falcon 9 launches' worth of bandwidth, on a ship that was maybe half loaded. Flight 15 (expected next month) will try to catch both the booster and the ship. Elon called that "more likely than not" to work.
- Compute scale. They're turning on about 200,000+ GB300s a month. Elon is highly confident of 10 GW of additional compute in 2027, and said 20 GW is "difficult, but not impossible". His reasoning is that SpaceX already casts turbine blades for rocket engines, so it can bring power online 12–18 months ahead of everyone else.
- The big claim. Elon put annual recurring revenue at US$500B–1T by the end of 2027. Then he joked he didn't want to give Bret a heart attack. That got a laugh, and the whole call felt like that: a team having fun because the numbers are working.
- Starlink Mobile. It's past 22M monthly users. The FCC has approved 15,000 mobile V2 satellites, and SpaceX has bought low-band spectrum, with a US mobile carrier on the way.
The merger committees
Asked about a Tesla merger, Elon said it was like "tap dancing through a minefield". Both companies have formed special committees of independent directors. He's conflicted, so he can't be in the room. He thinks combining them would be "a good idea", but no terms have been agreed and there's no guarantee. On the Tesla side it would need 50% of all shares. What struck me is how openly he talked about it here, compared with the next day. On Tesla's call he said he'd "said everything that should be said yesterday", and Tesla IR told analysts it wouldn't take any merger questions at all. That felt odd, and a bit unfair on Tesla shareholders. They'd need to vote on any deal, yet the real discussion happened on SpaceX's call. I hold both, so I'm happy either way, but I'm watching it closely.
The sceptic check
I'm bullish, but I also ran a sceptic check on the SEC release. These are the honest caveats:
- Net income flatters operations. Net income was US$4.40B, but operating income was only US$2.79B. About US$1.61B came from outside operations: US$1.025B of other income (US$561M of it related-party), US$198M of net interest on the IPO cash, and a US$390M tax benefit.
- Year to date is still a loss. The first nine months are still a US$413M loss. Management also flagged one-offs in the Q3 gross margin.
- The capex is enormous. Q3 capex was US$19.6B against US$8.8B of adjusted EBITDA, with US$16.4B of it on AI. Cash flow is roughly −US$35B for the nine months, funded by the IPO and debt.
- Some of the growth is bought. Part of the 161% growth comes from the Cursor acquisition sitting in AI revenue.
None of that changes my view. The upside is still bigger here than anywhere else I own. It's just good to know which bits of the headline are cash and which are accounting.
My long shot: one SPCX LEAP
Off the back of this call I'm placing a learning trade: 1 SPCX December 2028 US$450 call, with a limit order going in on Friday 23 October.
- Cost: the ask was about US$11.00 a share, so roughly US$1,100 for the contract (one contract covers 100 shares).
- Breakeven at expiry: about US$461. SPCX is at about US$159 today, so it needs to nearly triple just to get there.
- Implied volatility: about 54%, so I'm paying up for the chance of a big move.
- The dream scenario: if SPCX 10x's from here to about US$1,593, the call would be worth about US$114k at expiry. That's (1,593 − 450) × 100.
- The realistic risk: it can go to zero. Time decay eats it every day, and if SPCX is under US$450 in December 2028, the whole US$1,100 is gone. A merger would also adjust the contract terms.
I'm treating it as tuition: a small, fixed bet to learn how LEAPs behave over two years. I'll look at selling around mid-2028 rather than riding it to expiry. This is not advice.
Not financial advice. I'm a shareholder, so I'm biased.